Retirement isn't one big decision, it's a series of smaller, strategic ones made over time. The path is unique for every Shell professional, yet the milestones and key questions often look familiar. Each one shapes a piece of the outcome and evolves based on the order and timing of each decision. Understanding how one choice affects the next is where a clear plan makes all the difference. Use this roadmap to explore what’s ahead and see how each step can lead you closer to a confident retirement.
Gain clarity before you decide.
Before you can decide when or how to retire from Shell, it’s critical to understand the full picture of your financial life. That means knowing how much you've saved, what benefits you’ve earned, and what the account values are really worth in today’s dollars after taxes.
Some of the earliest questions we look at with clients regarding their non-Shell savings are:
Once you understand the different types of savings accounts, it’s time to look at what Shell provides. Your pension, 401(k), and BRP benefits each play a unique role in your retirement income and planning. Knowing how they work together and the mistakes to avoid with each one can make a big difference in your results.
Make the most of every remaining paycheck.
Before you hang up your hard hat, make sure every dollar you earn is working as hard as you do. Your final years at Shell can provide some of your biggest opportunities to boost savings in 401(k) contributions, backdoor Roth conversions, and additional savings vehicles. Small adjustments now can help create lasting flexibility once your paycheck stops. We've gathered some of our most popular savings resources for Shell professionals below.
| Savings Vehicle |
Important Consideration |
|
Shell Provident Fund |
There are additional catch-up contributions available for those over age 50, and a super-catch-up for those aged 60-63, over and above annual 401(k) contribution limits. |
|
IRA or Backdoor Roth Strategy |
Even if your income is too high to contribute to a Roth directly, the IRA + Backdoor Roth strategy can help you turn savings into tax-free growth over time. |
|
Health Savings Account |
The Shell HSA offers triple tax benefits (deductible contributions, tax-free investment growth, and tax-free withdrawals for qualified medical expenses) and converts to an IRA at age 65. |
|
Performance Shares |
Understanding how and when to sell your Shell stock compensation can help you reduce taxes and diversify your portfolio. |
|
GESPP |
The Shell GESPP’s lookback provision lets you buy company stock at a 15% discount, up to the annual maximum. |
Advisor Tip: Managing these plans is no simple feat. Talk to a financial professional before trying to implement the strategies outlined in these articles to avoid common tax triggers.
Leverage an exit package to unlock additional savings.
A severance package or special leave of absence can ease the shift out of Shell, but it also adds complexity. Learning how these plans affect your taxes and cash flow can help you make smarter decisions about timing your retirement. Learn more about these by clicking the links below.
Industry Disclosures: FTB is not a client of WJW and is being paid a monthly fee for their endorsements and collaboration. This compensation creates a material conflict of interest as FTB has an incentive to recommend WJW. FTB's comments may not be representative of any other person's experiences.
Make informed healthcare decisions early.
Shell retiree medical coverage can bridge the gap between your working years and Medicare, but eligibility and costs depend on your age, years of service, and how you separate from the company.
The plan isn’t automatic. You must meet specific service and age requirements at the time you retire.
Premiums, deductibles, and coverage options may differ from what you’re used to while employed, and once you or your spouse reach Medicare age, your Shell coverage becomes secondary. Reviewing your eligibility, timing your retirement date carefully, and understanding how healthcare fits into your broader financial plan are key steps to avoiding surprises and keeping your long-term costs manageable.
Additionally, Shell has two retiree healthcare plans depending on an employee's start date.
To learn more, click the link below that fits you best.
What lies beyond the numbers as you start your next chapter?
Retirement isn’t just about leaving work; it’s about discovering what’s next. Transitioning away from a long Shell career can open space for a new purpose, whether that means volunteering, consulting, mentoring, or simply having more time for what matters most.
Common ways our clients find purpose in retirement:
As our clients begin transitioning into their retirement, we work alongside them to explore ways they can align their wealth with what fills their cup. WJW CEO,
Nick Johnson, CFA®, CFP®, recently sat down with one of our clients to discuss the emotional side of transitioning to retirement. You can watch the whole conversation here.
Tim is a current client of WJW and is receiving promotional consideration for his business. This creates a conflict of interest because he has an incentive to provide a favorable review. His statements are not a guarantee of results and may not be representative of any other person's experience.
Turn experience into a consulting or self-employment opportunity.
After retiring from Shell, many people want to explore new ventures. Some people start consulting. Others turn a hobby into a small business or dive into real estate.
These endeavors can add purpose, flexibility, and extra income to your next chapter, but they also come with new financial and tax challenges. Our in-house tax team has helped many clients launch their businesses, sidestep common mistakes, and get their businesses off the ground with a strong start.
If you’re considering a new venture in retirement, reach out and our team can help you take the first step.
Put the plan to work while keeping more of what's yours.
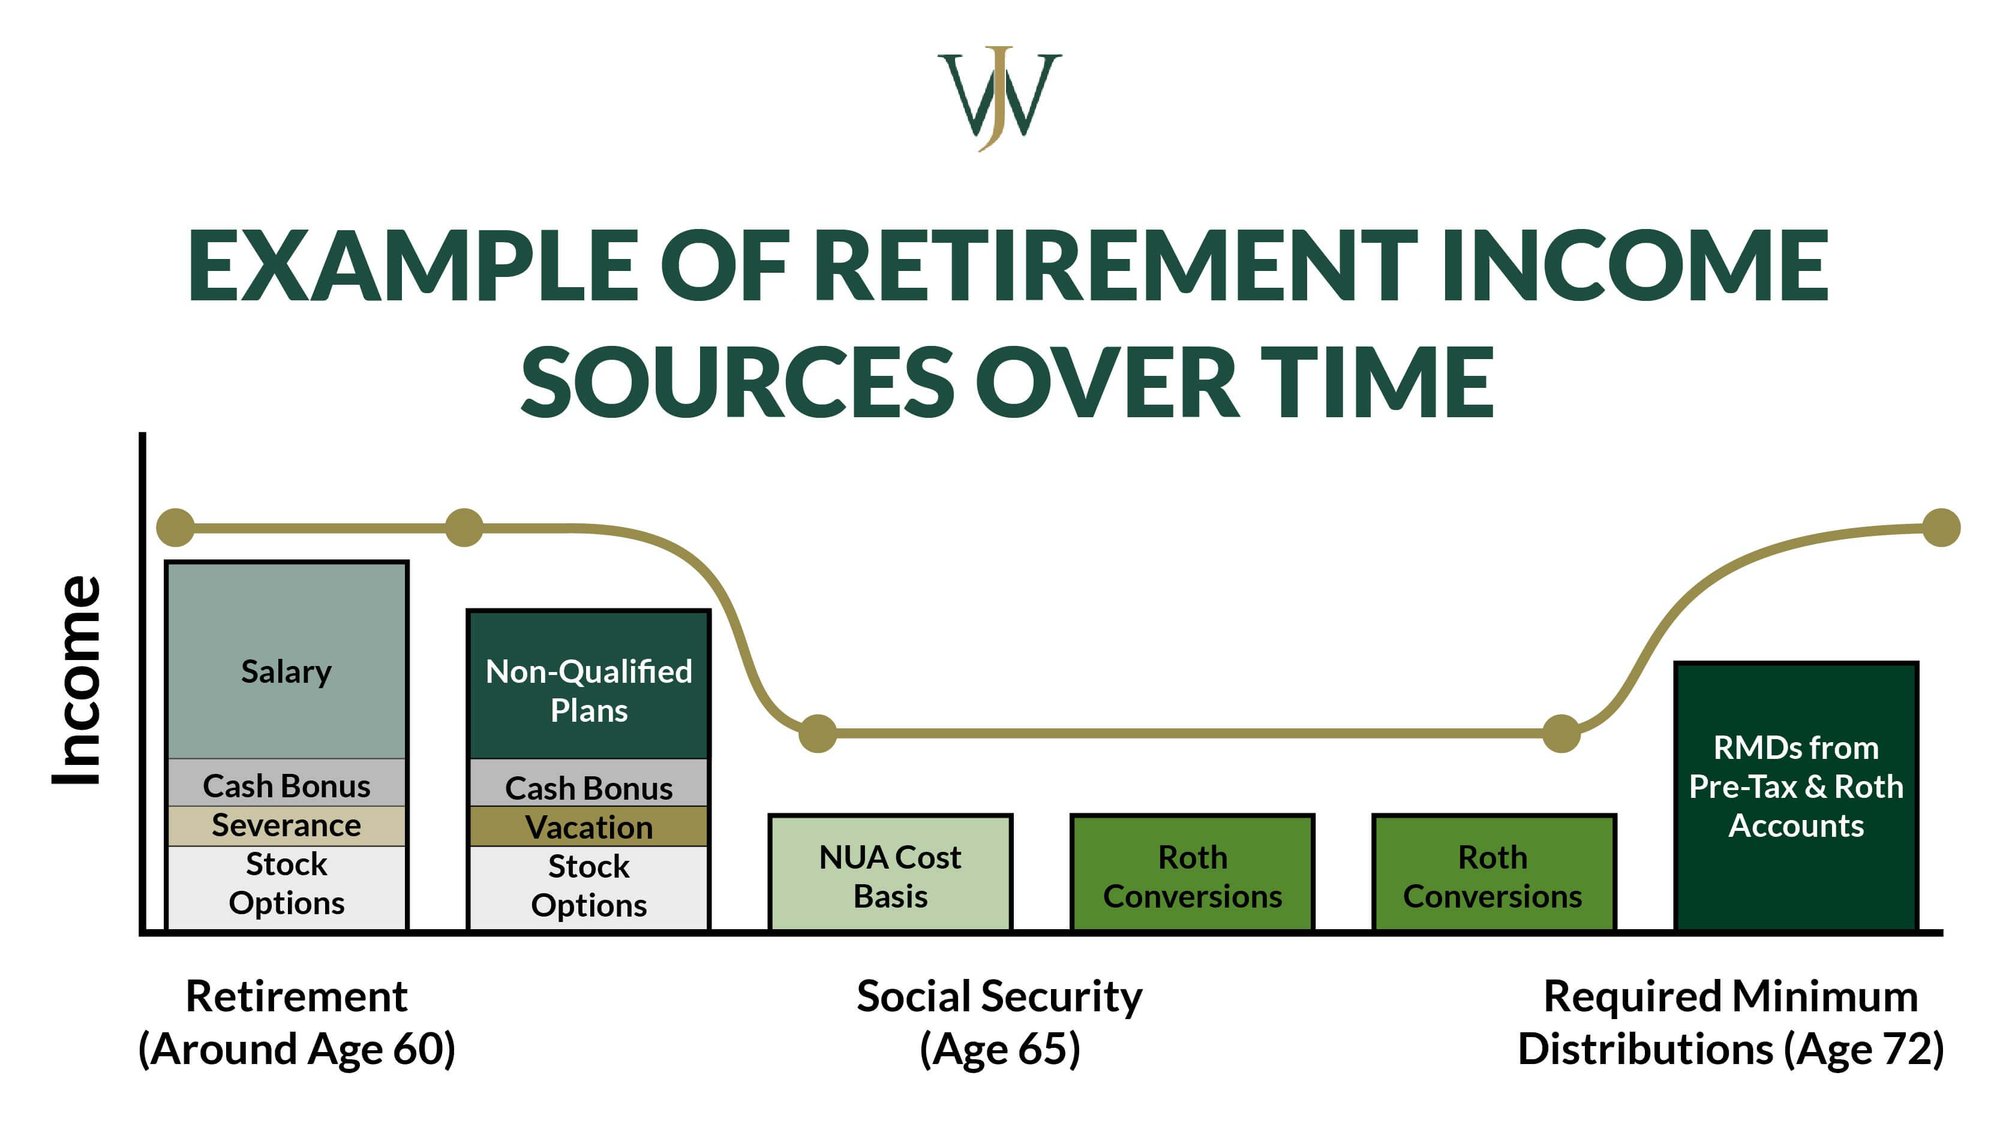
Knowing when and where to withdraw from in retirement can make a big difference in how long your money lasts. The sequence matters.
Drawing from taxable, tax-deferred, and Roth accounts in the right order can help you reduce taxes and preserve flexibility as you look to live off the funds in retirement. The right withdrawal order is designed to help minimize taxes, protect investment growth, and keep income steady year to year.
Bring it all together in a personalized session with one of our financial advisors specializing in Shell retirement planning.
For over 20 years, our advisors have helped Shell professionals connect important decisions and milestones into cohesive financial plans. We understand the unique challenges Shell employees face as they approach retirement: understanding your pension calculations, timing your BRP payouts, rediscovering purpose after a long career in energy, and developing smart strategies designed to minimize taxes along the way.
We offer a complimentary consultation with an advisor where you can review your existing benefits, severance packages, or compensation packages alongside your existing portfolio to create a comprehensive financial plan that helps take you where you want to go. Choose a time below to discuss your plan and goals with a member of our team.
This material is for general information only and is not intended to provide specific advice or recommendations for any individual. There is no assurance that the views or strategies discussed are suitable for all investors or will yield positive outcomes. Investing involves risks including possible loss of principal. Willis Johnson Wealth has a reasonable belief that this marketing does not include any false or material misleading statements or omissions of facts regarding services, investments, or client experiences. Willis Johnson Wealth has a reasonable belief that the content will not cause an untrue or misleading implication regarding the adviser's services, investments, or client experiences. Market projections or investment growth, including those in examples, are not indicative of future results, should not be considered specific investment advice, do not take into consideration your specific situation, and do not intend to make an offer or solicitation for the sale or purchase of any securities or investment strategies. Investments involve risk, including changes in market conditions, and are not guaranteed. Be sure to consult with a qualified financial advisor and/or tax professional before implementing any strategy discussed herein. Corporate benefits may change at any point in time. Be sure to consult with human resources and review Summary Plan Description(s) before implementing any strategy discussed herein. Willis Johnson Wealth is not a CPA firm. Willis Johnson Wealth is a SEC registered investment advisor.